Sources of finance
🎯What you need to be able to do
- Explain internal sources: personal funds (for sole traders), retained profit, sale of assets.
- Explain external sources: share capital, loan capital, overdrafts, trade credit, crowdfunding, leasing, microfinance providers and business angels.
- Evaluate the appropriateness of short- or long-term sources of finance for a given situation.
📚The business management
Internal sources
- Personal funds (for sole traders): the owner’s savings. No interest and no loss of control; limited in amount and puts personal wealth at risk.
- Retained profit: profit kept in the business after tax and dividends. No interest, no repayment, no dilution of ownership; but only available to profitable firms, may be insufficient, and shareholders may want dividends instead.
- Sale of assets: selling unwanted assets (old machinery, spare land, excess stock) or sale and leaseback (selling property and renting it back). Releases cash quickly; but the asset is lost and a sale under pressure may fetch a low price.
External sources
- Share capital: money raised by selling shares (for companies only). Large amounts, no interest, never repaid; but dilutes ownership and control, dividends expected, and going public is costly.
- Loan capital: medium- or long-term bank loans (and mortgages, bonds) repaid with interest over an agreed period. Owners keep control, fixed repayments aid planning; but interest must be paid whatever the profit, collateral often required, and high debt increases gearing and risk (3.6).
- Overdrafts: permission to withdraw more than the balance of a bank account, up to a limit. Flexible, interest only on the amount used; but high interest and can be withdrawn at short notice. For short-term cash gaps only.
- Trade credit: buying from suppliers and paying later (for example in 30 or 60 days). Effectively an interest-free short-term loan; but discounts for early payment are lost and delaying too long damages supplier relationships.
- Crowdfunding: raising small amounts from many people, usually online, in return for rewards, equity or loan repayments. Tests market demand and builds publicity; but campaigns can fail, take effort, and expose the idea to copying.
- Leasing: renting an asset (vehicles, equipment) for a fixed period instead of buying it. No large upfront cost, maintenance often included, easy to upgrade; but costs more in total and the asset is never owned.
- Microfinance providers: small loans (and savings services) to people and micro-businesses that banks exclude, often without collateral and using group guarantees. Vital for small entrepreneurs in developing economies; interest rates can be high and amounts are small.
- Business angels: wealthy individuals who invest their own money in start-ups for a share of ownership, often bringing experience and contacts. Risk capital and mentoring; but owners give up equity and some control. (Larger, later investments come from venture capital firms.)
Choosing the right source
Consider:
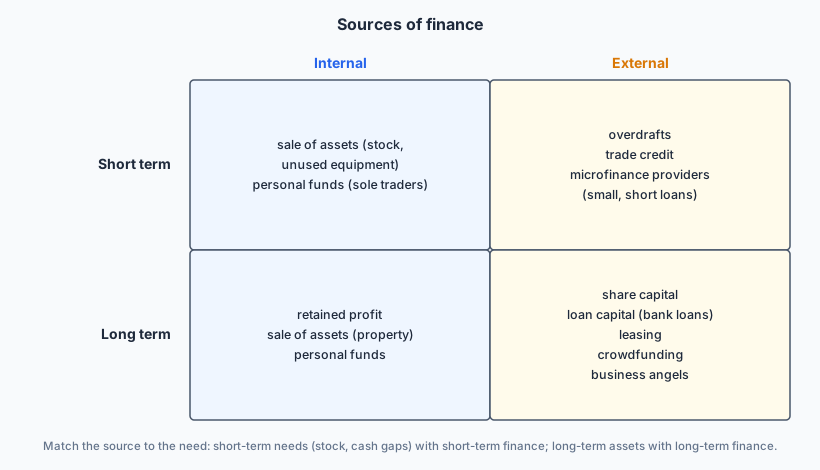
- Purpose and time period: match short-term needs (stock, cash gaps) with short-term finance, and long-term assets with long-term finance.
- Amount required.
- Cost: interest rates, fees, dividends expected.
- Legal form: only companies can issue shares.
- Control: equity dilutes ownership; loans do not.
- Existing debt and risk: a highly geared business may not be able to borrow more.
- Size, track record and collateral of the business.
✏️Worked example
(a) Personal funds or microfinance: small amount, owner has no collateral; microfinance (or Indonesia’s KUR micro-loans) suits micro-enterprises.
(b) Overdraft: a short-term, temporary gap that revenue will soon cover; interest only on what is used.
(c) Share capital (a new share issue) and/or long-term loan capital: a very large, long-term investment; the choice depends on current gearing and whether shareholders accept dilution.
(d) Business angels: banks rarely lend to loss-making start-ups; angels accept high risk in return for equity and bring expertise and contacts.
📝Practise
Work through these on paper, then reveal the answer.
1. [2 marks] Define the term trade credit.
2. [2 marks] Distinguish between an overdraft and a bank loan.
3. [4 marks] Explain one advantage and one disadvantage of retained profit as a source of finance.
4. [4 marks] Explain why leasing may be more appropriate than buying for a delivery company’s vans.
5. [4 marks] Explain two benefits of crowdfunding for a new social enterprise.
6. [10 marks] A family-owned private company needs $2 million to open a factory. Discuss whether it should use loan capital or share capital.
Loan capital: the family keeps full ownership and control; interest is tax-deductible in many countries; fixed repayments; but interest must be paid even if the factory underperforms, collateral required, gearing rises and adds risk if interest rates rise.
Share capital: as a private company, it can sell shares to selected investors (not the public); no repayment or interest; investors share risk and may bring expertise; but ownership and control are diluted and profits shared.
Judgment: depends on current gearing, the stability of expected profits, interest rates and how much the family values control; a mix (part loan, part equity) may balance risk and control.
🔗Go deeper — other people’s work
These are external resources, not mine. If one stops working, tell me and everything above it on this page still stands.
- Kiva — a microfinance lending platform showing real small-business loans worldwide.
- Kitabisa and other crowdfunding platforms — see how campaigns are structured.
- OJK (Indonesia’s Financial Services Authority) — information on regulated lending and investment.