Final accounts
🎯What you need to be able to do
- Explain the purpose of accounts to different stakeholders.
- Construct and interpret a profit and loss account and a balance sheet.
- Explain different types of intangible assets.
- HL Calculate depreciation using the straight-line and units-of-production methods, and evaluate the appropriateness of each.
📚The business management
Why stakeholders use accounts
- Shareholders and potential investors: profitability, dividends, growth; should they buy, hold or sell?
- Managers: monitor performance, set budgets, plan decisions.
- Employees and unions: job security, the ability to pay higher wages.
- Lenders (banks): can the business repay loans and interest? What collateral does it have?
- Suppliers: will they be paid if they offer trade credit?
- Government and tax authorities: tax owed; compliance with the law.
- Customers: will the business survive to provide warranties and supplies?
- Competitors: benchmark their own performance.
The profit and loss account
The profit and loss account (income statement) shows the business’s revenue and costs over a period, usually a year, and therefore its profit or loss.
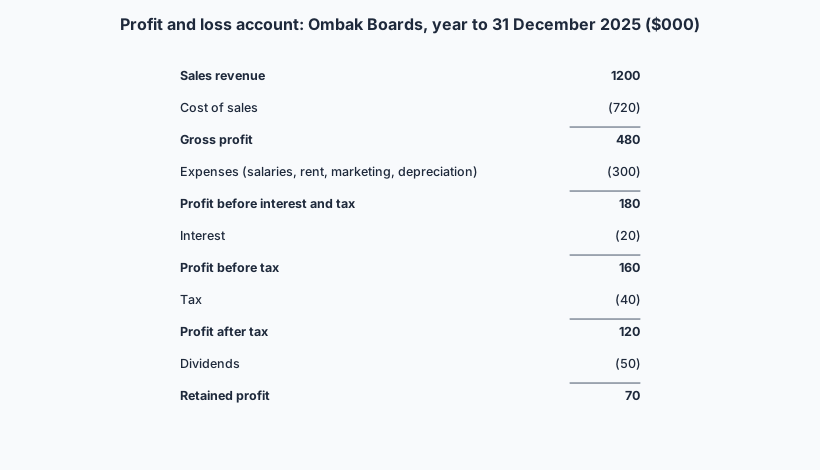
- Sales revenue − cost of sales (direct costs of the goods sold: materials, direct labour) = gross profit.
- Gross profit − expenses (overheads: salaries, rent, marketing, depreciation) = profit before interest and tax.
- − interest = profit before tax; − tax = profit after tax.
- − dividends = retained profit, which is added to retained earnings on the balance sheet.
Cost of sales = opening stock + purchases − closing stock.
The balance sheet
The balance sheet (statement of financial position) is a snapshot of what a business owns (assets) and owes (liabilities) at one point in time, and how it is financed (equity).
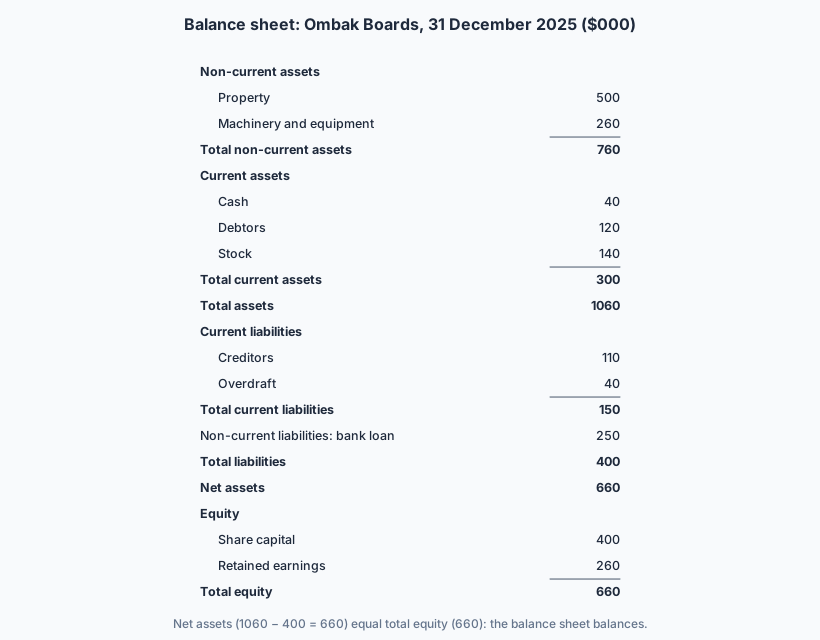
- Non-current assets: held for more than a year: property, machinery, vehicles, and intangible assets.
- Current assets: expected to be turned into cash within a year: cash, debtors (money owed by customers), stock.
- Current liabilities: due within a year: creditors (money owed to suppliers), overdrafts, short-term loans.
- Non-current liabilities: due after more than a year: long-term loans, mortgages.
- Net assets = total assets − total liabilities.
- Equity = share capital + retained earnings (for sole traders and partnerships, the owners’ capital). Net assets = equity.
Intangible assets
Intangible assets are non-physical assets that have value because they generate future income:
- Patents: exclusive rights to an invention for a period.
- Copyrights: rights over creative work (software, music, books).
- Trademarks: protected names, logos and slogans.
- Goodwill: the value of a business’s reputation, customer base and relationships beyond its net assets, recorded when a business is bought for more than the value of its net assets.
- Also licences, franchises and brand names (5.8 covers intellectual property).
They are hard to value objectively, and their value can change quickly (a scandal damages a brand overnight).
Depreciation HL
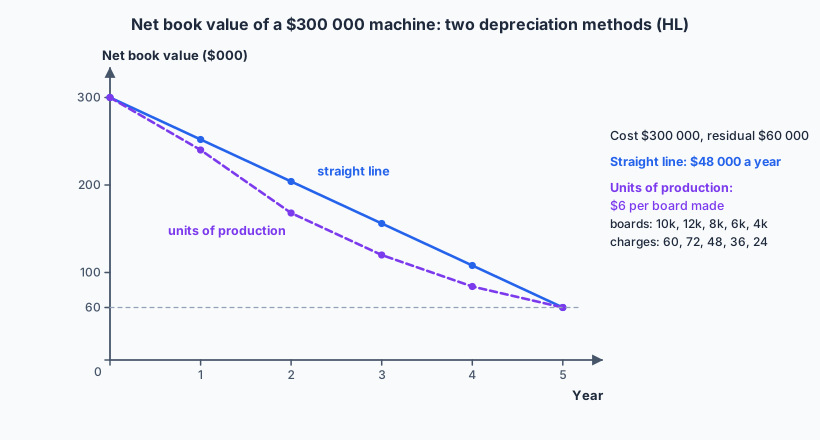
Depreciation is the fall in value of a non-current asset over its useful life, through wear and tear or obsolescence. The cost of the asset is spread over its life as an expense in the profit and loss account, and the asset’s net book value (cost minus accumulated depreciation) falls on the balance sheet.
the same amount each year. Simple and easy to compare; suits assets that are used evenly over time (buildings, furniture). Ignores how much the asset is actually used.
depreciation depends on how much the asset is used (units produced, hours, kilometres). Matches cost to use, so suits machines and vehicles whose wear depends on usage; needs a reliable estimate of total output and records of use.
✏️Worked example
(a) ($000) Gross profit = 1200 − 720 = 480. PBIT = 480 − 300 = 180. Profit before tax = 180 − 20 = 160; profit after tax = 160 − 40 = 120; retained profit = 120 − 50 = 70.
(b) Total assets = 760 + 300 = 1060. Total liabilities = 150 + 250 = 400. Net assets = 1060 − 400 = 660. Equity = 400 + 260 = 660. They are equal.
(c) Straight line: (300 000 − 60 000) ÷ 5 = $48 000 a year. Units of production: 240 000 ÷ 40 000 = $6 per board, so $60 000, $72 000, $48 000, $36 000 and $24 000. Both leave a net book value of $60 000 after 5 years.
📝Practise
Work through these on paper, then reveal the answer.
1. [2 marks] Define the term current assets.
2. [2 marks] A firm has sales of $850 000, opening stock $60 000, purchases $400 000 and closing stock $70 000. Calculate gross profit.
3. [4 marks] A company has non-current assets $500 000, current assets $180 000, current liabilities $90 000, a long-term loan $150 000 and share capital $300 000. Calculate net assets and retained earnings.
4. [4 marks] Explain why a bank and a shareholder might look at different parts of a company’s final accounts.
5. HL [4 marks] A delivery van costs $45 000 and will be sold for $5000 after 4 years. Calculate straight-line depreciation and the net book value after 2 years.
6. HL [4 marks] Explain why the units-of-production method may be more appropriate than straight line for a delivery van.
🔗Go deeper — other people’s work
These are external resources, not mine. If one stops working, tell me and everything above it on this page still stands.
- Indonesia Stock Exchange — listed companies’ annual reports with real income statements and balance sheets.
- AccountingCoach — tutorials on the balance sheet, income statement and depreciation.
- IFRS Foundation — the international standards that most published accounts follow.