Costs and revenues
🎯What you need to be able to do
- Explain fixed, variable, direct and indirect (overhead) costs, using examples.
- Explain total revenue and revenue streams, using examples.
📚The business management
Fixed and variable costs
costs that do not change with the level of output in the short run: rent, salaries, insurance, loan interest, depreciation. Paid even if nothing is produced.
costs that change directly with output: raw materials, packaging, piece-rate wages, sales commission, energy used in production. Zero when output is zero.
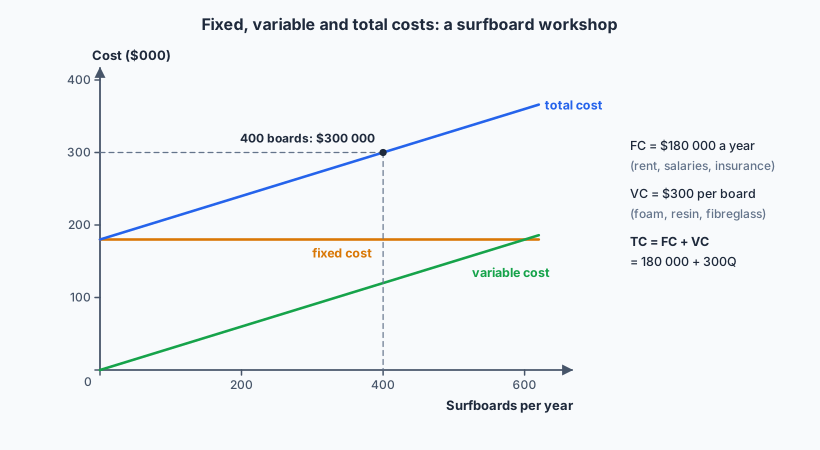
Some costs are semi-variable: a fixed part plus a variable part, such as a phone bill with a monthly fee plus usage, or a salary plus overtime. Fixed costs are fixed only within a range and time period: expanding beyond a factory’s capacity means renting another building, a step up in fixed costs.
Direct and indirect costs
costs that can be clearly identified with a particular product or department: the wood in a table, the wages of the carpenter who made it.
costs that cannot be traced to one product because they are shared: office rent, managers’ salaries, marketing for the whole brand, accounting, security. Must be shared out (allocated) between products, which requires judgment.
The two classifications overlap: direct costs are usually variable (materials), but not always; overheads are usually fixed (rent), but not always (electricity for the whole building rises with overall activity).
Revenue
A revenue stream is a distinct source of revenue. Businesses increasingly earn from several, which spreads risk:
- Sales of goods and services (the main stream for most businesses).
- Subscriptions (streaming, software, gym memberships).
- Advertising (social media platforms, news sites).
- Commission and fees (booking platforms, ride-hailing apps taking a percentage).
- Licensing and franchising fees and royalties.
- Rental or leasing of assets.
- Sponsorship, donations and grants (sports clubs, social enterprises, NGOs).
- Interest and dividends from investments.
A surf school, for example, might earn from lessons, board rental, merchandise, café sales and a commission from a nearby hotel for booking guests.
✏️Worked example
(a) TC = 180 000 + 300 × 400 = 180 000 + 120 000 = $300 000. TR = 800 × 400 = $320 000. Profit = 320 000 − 300 000 = $20 000.
(b) Foam and resin: variable, direct. Rent: fixed, indirect. Shaper paid per board: variable, direct. Owner’s salary: fixed, indirect. Website hosting: fixed, indirect.
📝Practise
Work through these on paper, then reveal the answer.
1. [2 marks] Define the term variable cost.
2. [2 marks] Distinguish between direct and indirect costs.
3. [2 marks] A bakery has fixed costs of $4000 a month and variable costs of $1.20 per loaf. Calculate the total cost of producing 5000 loaves.
4. [2 marks] The bakery sells loaves at $2.50. Calculate total revenue and profit at 5000 loaves.
5. [4 marks] Explain two revenue streams a music streaming app could have.
6. [4 marks] Explain why a business might want several revenue streams.
🔗Go deeper — other people’s work
These are external resources, not mine. If one stops working, tell me and everything above it on this page still stands.
- AccountingCoach — cost behaviour: fixed, variable and mixed costs.
- Strategyzer — the Business Model Canvas, including revenue streams.
- Tutor2u — revision notes on costs and revenues.